Credit Score:Expanding Financial Access Across West Africa
Lalikan transforms informal savings into actionable credit data, helping financial institutions assess credit scores and expand financial access to millions of underserved people across West Africa.
Discover our solutionWe Build Credit Infrastructure for the Informal Economy
Lalikan is a financial technology (fintech) company that empowers banks, microfinance institutions, and fintechs with the infrastructure and credit scores they need to serve West Africa’s largely informal economy.
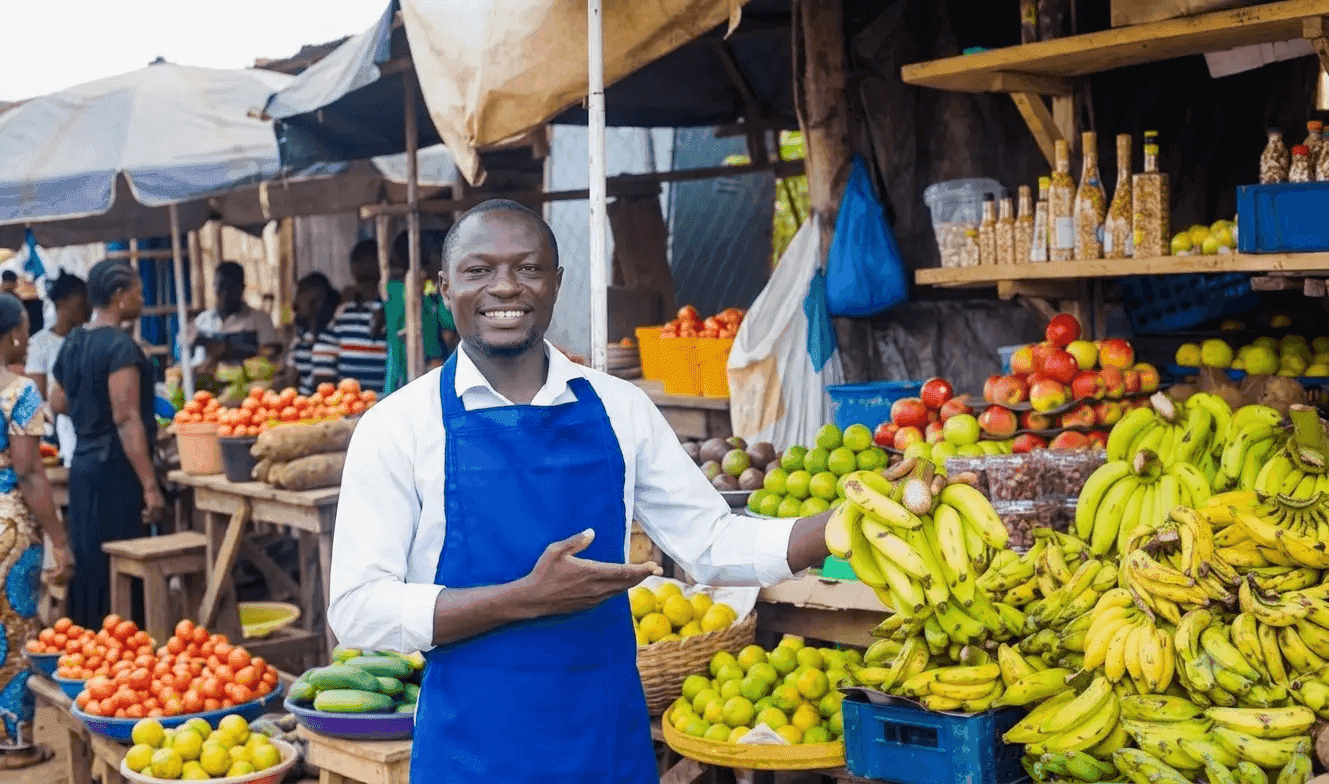
We don’t lend money; we make credit assessment more accessible by transforming informal savings activities, including tontines, susu, and ajo, into verified, reliable, and compliant digital credit histories.
Our solution
Credit Scores That Reveal Hidden Creditworthiness
Across West Africa, millions of informal savers build strong financial track records through tontines but lack formal credit histories. Lalikan transforms this overlooked savings data into reliable credit scores, helping financial institutions assess creditworthiness and expand access to financial services.
Our markets
Building Credit Infrastructure Across West Africa
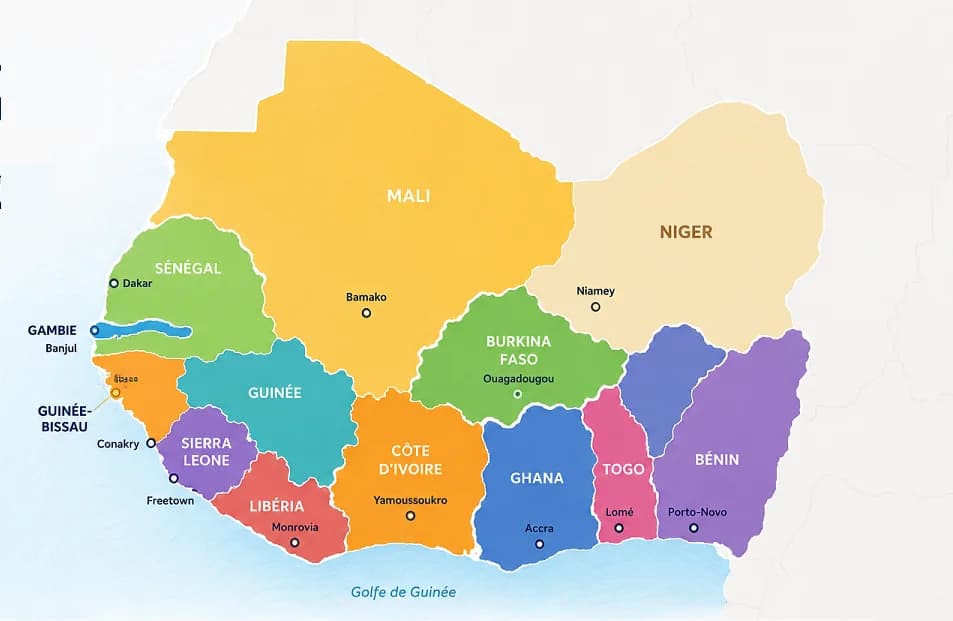
Lalikan serves markets across West Africa, including Côte d’Ivoire, Senegal, Burkina Faso, Benin, Togo, Mali, Niger, Guinea-Bissau, Nigeria, and Ghana. Our credit infrastructure is designed around local financial practices, helping institutions assess creditworthiness and expand access to financial services.
From invisible to credit in 4 steps.
Lalikan does not lend money. We provide financial institutions the infrastructure they need to serve millions of new clients.
Capture
The collector records contributions via the Lalikan app – even offline.
Aggregate
Data is consolidated to create a verified 12-month savings history.
Score
Our algorithm generates a reliable credit score (0 to 100) based on savings regularity, tenure and other information.
Serve
Financial institutions use this score to confidently lend to previously invisible populations.
One Credit Score Infrastructure for Every Financial Institution
Lalikan is a SaaS platform built for microfinance institutions (MFIs), banks, and fintechs. We don’t provide loans; we deliver reliable credit data and credit scores that help financial institutions assess risk and extend responsible lending to underserved populations across West Africa.
Basic
30-day free trialStarter tier for small teams getting onboarded.
- Up to 20 agents
- 5 GB storage
- Registration
- Reports & Analytics
Pro
Growing teams that need collections and scoring.
- Up to 60 agents
- 200 GB storage
- Registration
- Reports & Analytics
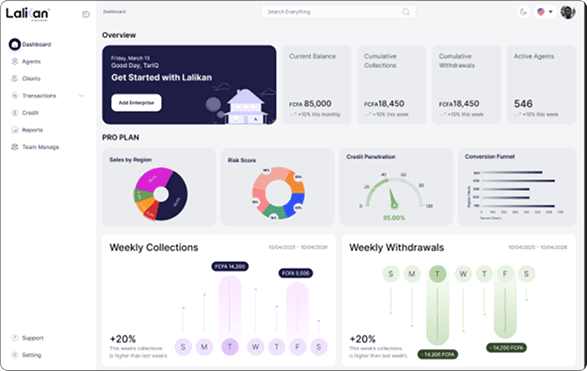
- Collect / Withdraw
- Transaction history
- Predictive scoring
Enterprise
Full feature set with unlimited agents and storage.
- Up to 20 agents
- 50 GB storage
- Registration
- Reports & Analytics
- Collect / Withdraw
- Transaction history
- Predictive scoring
- Credit simulation
- Payment tracking
- Credit application
- Mobile money (MoMo)
- Risk management
- Advanced tools
- Provisions
- Personalized dashboard
60-day free pilot – risk-free, no commitment.
Credit scoring for the informal economy, explained.
Straight answers to what lenders, risk teams and compliance officers ask us most.
What is alternative credit scoring?
Traditional credit scoring relies on bank statements, payslips and loan records that most people in West Africa simply do not have. Alternative credit scoring looks at other proof of financial discipline. For Lalikan, that proof is savings behaviour: how often a person contributes, how consistently, and for how long. Turned into a single score, it lets a lender judge risk for someone who has never held a bank account.
Why are tontine savers a good credit risk?
Contributing to a tontine, susu or ajo every day or every week for months is a commitment kept in public, with neighbours and family watching. That regularity is exactly what a lender wants to see before granting credit. Until now it was written by hand in collectors’ notebooks, invisible to anyone outside the group.
Who is Lalikan built for?
Our customers are regulated financial institutions: microfinance institutions, commercial banks and fintech lenders operating in West Africa. Savers and small businesses benefit indirectly, through better access to credit from those institutions, but they do not sign up with Lalikan or apply for loans through us.
Who decides whether a client gets a loan?
Always the financial institution. Lalikan supplies a score and the verified history behind it; the lender combines that with its own policies, its knowledge of the client and its regulatory obligations before making any decision.
How is personal and financial data protected?
Client data is processed on behalf of each partner institution, under a data processing agreement and in line with the ECOWAS Supplementary Act on personal data protection and national rules such as those of ARTCI in Côte d’Ivoire and the CDP in Senegal. We never sell data or share it with third parties.
How does credit scoring help expand financial inclusion?
A lender cannot serve a client it cannot assess. By expanding the information available about informal savers, a score lowers the uncertainty that keeps them out of the formal system, so institutions can offer smaller first loans, learn from repayment, and grow the relationship over time.
Is Lalikan available today?
Lalikan is in its pre-launch phase. Institutions can already request a demo and join a pilot programme to test the platform on their own portfolio before commercial launch.
The informal economy, decoded.
Every month, receive our analysis on financial inclusion, alternative data, and credit trends in West Africa. Direct from our Observatory.